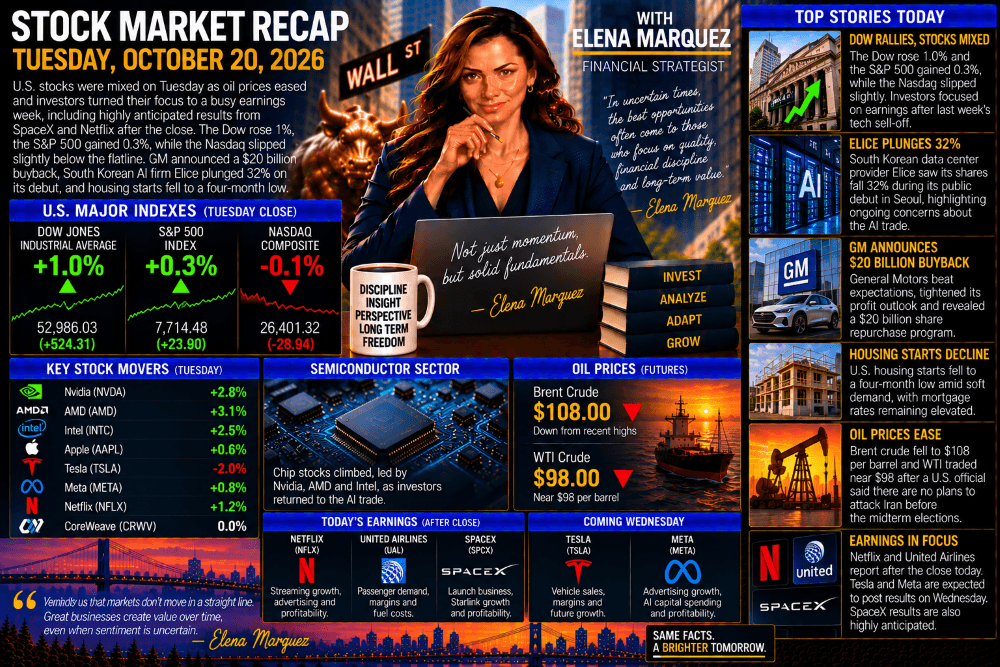
Tuesday | Dow rallies, oil prices ease, and investors turn their attention to corporate earnings
Wall Street finished Tuesday with mixed results as investors shifted their attention from last week’s technology selloff toward corporate earnings.
The Dow Jones Industrial Average gained approximately 1%, while the S&P 500 advanced 0.3%. The technology-heavy Nasdaq slipped slightly below the flatline.
Oil prices eased as geopolitical tensions showed signs of stabilizing, providing some relief from recent inflation concerns.
Meanwhile, General Motors announced a massive $20 billion share repurchase program, South Korean AI infrastructure company Elice suffered a disappointing stock-market debut, and housing construction slowed amid elevated mortgage rates.
The central question for investors is whether corporate earnings can restore confidence in a market increasingly concerned about AI valuations, debt and interest rates.
Market performance
Dow Jones
+1.0%
Tuesday, Oct. 20
S&P 500
+0.3%
Tuesday, Oct. 20
Nasdaq
Slight decline
Tuesday, Oct. 20
Approximate index changes from the supplied market update.
1. The Dow Outperforms as Investors Rotate Away From Technology
The Dow’s approximately 1% gain stood out against the Nasdaq’s slight decline.
This continues a trend that became apparent last week.
Investors are becoming more selective about technology stocks, particularly companies whose valuations depend heavily on future AI growth.
The Nasdaq lost approximately 4.5% last week, its worst performance since late June.
But the Dow actually gained 0.7% over the same period.
That divergence suggests investors aren’t necessarily abandoning stocks altogether.
Instead, they may be shifting money toward more established businesses with predictable earnings, stronger cash flow and less dependence on expensive financing.
This is known as sector rotation.
It can be a healthy development if market gains become less dependent on a handful of technology companies.
However, a sustained rotation could also signal that investors are becoming more cautious about the broader economic outlook.
2. AI Concerns Deepen After Elice’s Disappointing Debut

One of Tuesday’s most revealing developments occurred in South Korea.
AI data center provider Elice reportedly plunged approximately 32% during its first day of public trading in Seoul.
The disappointing debut highlights the growing skepticism surrounding companies involved in AI infrastructure.
For much of the past few years, investors enthusiastically financed businesses promising to build the computing capacity required for artificial intelligence.
The opportunity appeared enormous.
AI developers need powerful processors, large data centers, advanced networking equipment and enormous amounts of electricity.
But these investments are extremely expensive.
And many companies must spend heavily before generating sufficient revenue to cover their costs.
The market is beginning to distinguish between AI companies with proven profitability and those relying on future growth expectations.
Elice’s difficult debut follows last week’s sharp declines in companies such as CoreWeave, Nebius and IREN.
These businesses operate in different markets, but they share exposure to the economics of AI infrastructure.
The AI revolution may continue expanding rapidly, but investors are becoming less willing to finance growth at any price.
3. General Motors Announces a $20 Billion Buyback

General Motors delivered one of Tuesday’s major corporate announcements.
The automaker reported third-quarter results that exceeded expectations, tightened its profit outlook and unveiled a $20 billion share repurchase program.
A share buyback allows a company to purchase its own stock in the open market or through other transactions.
When a company reduces the number of shares outstanding, each remaining share represents a larger ownership percentage of the business.
Buybacks can also increase earnings per share, assuming profits remain unchanged.
For investors, a large repurchase announcement can signal management’s confidence in the company’s financial position.
But buybacks aren’t automatically beneficial.
Their value depends partly on the price the company pays for its shares.
Repurchasing stock when it is undervalued can create substantial value.
Buying shares at inflated prices may be a poor use of capital.
GM’s announcement is particularly interesting because it contrasts with the enormous capital spending underway in the AI industry.
While some technology companies are borrowing heavily to finance expansion, GM is committing substantial resources to returning capital to shareholders.
Different industries, different priorities.
4. Housing Construction Falls to a Four-Month Low
The US housing market continues to struggle with elevated borrowing costs.
New housing starts declined to their lowest level in four months, according to Tuesday’s economic data.
Housing starts measure the number of residential construction projects that begin during a given period.
They provide an important indication of confidence among homebuilders and the strength of housing demand.
When mortgage rates rise, monthly payments become more expensive.
That reduces affordability for potential buyers.
Homebuilders may respond by delaying new construction, offering incentives or reducing prices.
Higher financing costs can also make development projects less attractive.
The slowdown in housing starts is another reminder that interest rates affect the real economy, not just financial markets.
5. Oil Prices Ease, but Energy Risks Remain
Brent crude
~$108
Per barrel
WTI crude
~$98
Per barrel

Oil prices declined modestly Tuesday.
Brent crude traded near $108 per barrel, while West Texas Intermediate remained around $98.
The decline followed comments from a US official reiterating that President Trump did not plan to attack Iran before the November midterm elections.
That statement may have reduced some immediate concerns about further military escalation.
However, the geopolitical situation remains uncertain.
Recent attacks on energy infrastructure and oil tankers have raised concerns about global supply disruptions.
The Strait of Hormuz remains particularly important because of the large volume of oil transported through the region.
A sustained decline in energy prices could help ease inflation.
But prices near $100 per barrel still represent a substantial cost for consumers and businesses.
6. Netflix and SpaceX Earnings Attract Attention
Tuesday’s earnings calendar included two closely watched companies: Netflix and SpaceX.
Netflix was scheduled to release its quarterly results after the market closed.
Investors are focused on advertising revenue, subscription pricing, customer engagement and profitability.
Netflix has become an important example of a technology-driven business that generates substantial revenue directly from customers.
Its results can provide insight into consumer spending and the economics of digital entertainment.
SpaceX was also expected to report results, according to the supplied market update.
Investors are interested in its launch business, satellite communications and the growth of Starlink.
SpaceX operates in a capital-intensive industry requiring substantial investment in rockets, satellites, manufacturing and launch infrastructure.
Its financial performance could offer another perspective on the challenges of financing rapid technological expansion.
These earnings discussions reflect the pre-report market update. No after-hours results are included here.
7. United Airlines Reports After the Close
United Airlines was another company scheduled to release quarterly earnings Tuesday evening.
Airlines have been particularly sensitive to rising fuel prices.
When crude oil rises, jet fuel costs can increase, putting pressure on profit margins.
However, strong passenger demand and higher ticket prices can sometimes offset those expenses.
Investors will be watching whether United can maintain profitability despite elevated energy costs.
They will also look for commentary about business travel, international demand and future capacity.
8. Tesla and Meta Are Next
Wednesday will bring another important test for the technology sector.
Tesla and Meta are both expected to report quarterly results after the closing bell.
Tesla: Can vehicle sales support its valuation?
Tesla investors will focus on vehicle deliveries, automotive profit margins, pricing and spending on autonomous-driving technology.
The company recently unveiled a redesigned Roadster featuring ambitious performance claims.
But investors will want to see whether Tesla can translate its technological ambitions into sustainable profits.
Meta: Is AI spending generating returns?
Meta may be even more important for the broader AI trade.
The company is investing heavily in artificial intelligence infrastructure.
But unlike some specialized AI data center operators, Meta has a large and profitable advertising business.
Investors will want to know whether AI investments are improving advertising performance, user engagement and revenue growth.
They will also examine management’s plans for future capital expenditures.
If Meta reports strong results and demonstrates that its AI investments are creating measurable value, it could help restore confidence in the sector.
If spending continues rising without clear evidence of returns, investors may become more cautious.
9. What I’m Watching Next
Three developments could determine the market’s direction over the coming sessions.
Corporate earnings: Netflix, United Airlines, Tesla and Meta will provide insight into consumer demand, business profitability and the economics of technology investment.
AI financing: The disappointing debut of Elice and recent weakness in CoreWeave highlight growing concern about the debt and capital required to build AI infrastructure.
Oil prices and interest rates: Lower oil prices could help inflation expectations, but energy markets remain vulnerable to geopolitical developments.
Investors will also be watching whether the Dow continues outperforming the Nasdaq.
A sustained rotation away from technology could significantly change market leadership.
The Bottom Line
| Indicator | October 20 |
|---|---|
| Dow Jones | Approximately +1.0% |
| S&P 500 | Approximately +0.3% |
| Nasdaq | Slightly negative |
| Elice IPO debut | Approximately −32% |
| GM share buyback | $20 billion |
| Housing starts | Four-month low |
| Brent crude | ~$108/barrel |
| WTI crude | ~$98/barrel |
| Netflix earnings | Tuesday after close |
| Tesla and Meta earnings | Wednesday after close |
Tuesday’s market action revealed a growing divide between technology stocks and the rest of the market.
The Dow advanced strongly while the Nasdaq struggled.
Investors welcomed GM’s substantial share repurchase announcement but remained cautious about AI infrastructure companies that require enormous capital investments.
Meanwhile, declining housing construction demonstrated the economic consequences of elevated borrowing costs.
The coming earnings reports will help determine whether the market’s renewed caution toward technology is justified.
The AI revolution may be transforming the economy, but investors are increasingly focused on something much more traditional: profits, cash flow and financial discipline.
Other Stock Market blog posts
Leave a Reply