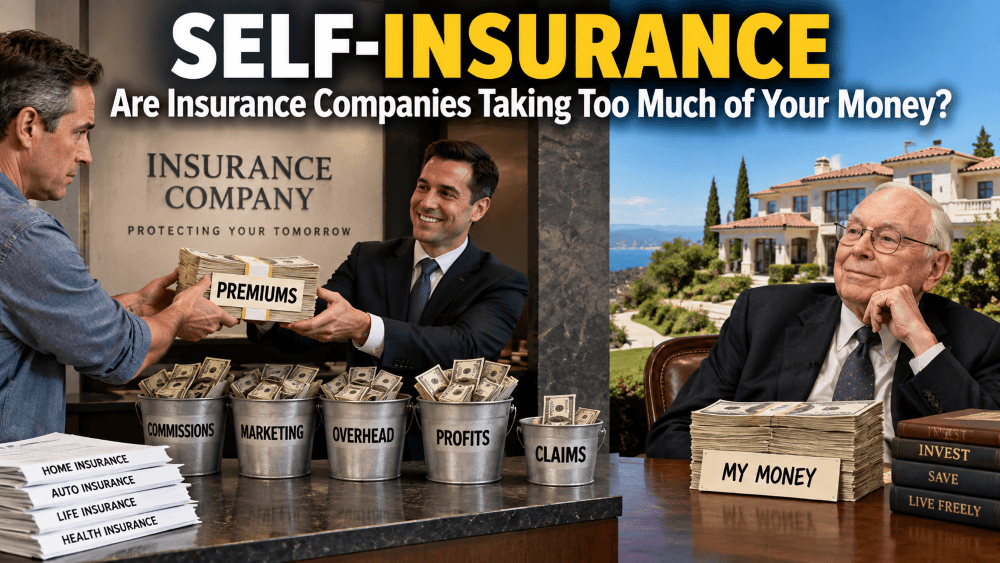
“In my own life, I’m a big self-insured and so is Warren,” Charlie Munger said, referring to himself and Warren Buffett.
Self-insurance sounds risky until you understand what Charlie Munger meant by it.
The billionaire investor and longtime Berkshire Hathaway vice chairman believed insurance should primarily protect you from losses you cannot afford to absorb yourself. If a loss would merely be annoying rather than financially devastating, Munger questioned why you should continually pay an insurance company to assume that risk.
That distinction is much more important than simply asking, “Should I have insurance?”
The better question is:
Which risks could destroy me financially, and which risks can I afford to pay for myself?
Charlie Munger Didn’t Insure His House Against Fire
At the Daily Journal Corporation annual shareholder meeting in February 2023, Munger was asked about companies choosing to self-insure certain risks.
His answer quickly became personal.
“In my own life, I’m a big self-insured and so is Warren.”
Munger explained that carrying fire insurance on his house no longer made financial sense to him because, if the house burned down, he had enough money to rebuild it.
His rule was remarkably simple:
“You should insure against things you can’t afford to pay for yourself.”
And then came the kind of comment that made Munger famous.
After explaining that he could simply write a check and rebuild his house, he joked that “all intelligent people” did things his way, before softening the statement slightly to say they should do it his way.
Munger also said that, with one exception, he had never carried collision insurance on his cars and that after becoming wealthy, he stopped carrying fire insurance on his houses.
His reasoning wasn’t that insurance companies provide no useful service.
It was that insurance has a cost.
What You’re Really Paying for When You Buy Insurance
For a short period of my life, I, Alain Guillot, worked as an insurance salesperson.
That experience changed the way I think about insurance.
Part of my job was to present catastrophic scenarios to prospective customers. We were trained to make people imagine what could happen if they were uninsured.
What if you died?
What would happen to your family?
What if your property was destroyed?
What if some terrible event wiped out everything you had worked for?
Then came the close:
For X dollars per month, you and your family can have peace of mind.
It was effective because fear is an extraordinarily powerful sales tool.
But consider what happens to the premium after the customer writes the check.
The money doesn’t simply sit somewhere waiting to pay that customer’s future claim.
An insurance premium has to support claims, employees, administration, technology, commissions, marketing, regulatory expenses, fraud and fraud prevention, reserves, taxes and other operating costs. A private insurer also generally needs to earn an adequate return on its capital.
And after paying all those expenses, it’s to the insurance company interest to pay as little as legally possible, to make your claim burdensome, and if possible to deny your claim. They less they pay out, the more money go to their shareholders.
If you can comfortably assume that risk yourself, self-insurance deserves consideration.
Self-Insurance Is Really About Financial Independence
This is where I think Munger’s idea becomes interesting for ordinary people.
You don’t need to be a billionaire to practice self-insurance.
You probably can’t self-insure a $2 million liability claim. But perhaps you can self-insure a $1,000 car repair.
Maybe you can’t afford to rebuild your entire house after a fire. But you can afford a $2,500 or $5,000 deductible instead of a $500 deductible.
As your savings increase, your dependence on insurance for relatively small losses can decrease.
That is one of the overlooked benefits of financial independence.
Savings don’t just generate investment returns. Savings allow you to assume risks that you previously had to pay someone else to assume.
The fewer dollars you pay an insurance company, the more money you get to keep to yourself and your family.
How Self-Insurance Can Work for Ordinary People
There are several practical ways to apply Munger’s philosophy without recklessly eliminating important protection.
1. Build a large emergency fund
The first step toward self-insurance is liquidity.
If a $2,000 unexpected expense forces you to use a credit card at 20% interest, you’re probably not ready to self-insure many risks.
If you have substantial liquid savings, the calculation changes.
Your emergency fund effectively becomes your personal insurance company.
2. Increase your deductibles
This may be one of the simplest applications of self-insurance.
Instead of paying higher premiums so the insurer absorbs the first few hundred dollars of a loss, consider whether you could comfortably cover a larger deductible yourself.
You insure the catastrophe while self-insuring the smaller loss.
That strikes me as a sensible compromise.
3. Drive an inexpensive car
I own a bicycle and I use public transportation, so I don’t pay for car insurance, but when I used to be a car owner, I have long preferred the idea of owning a relatively inexpensive car.
If your car is worth $5,000, losing it would hurt. But depending on your financial position, replacing it might not be catastrophic.
If your car is worth $80,000 and financed, you have created a much larger financial exposure—and potentially a much larger insurance bill.
An inexpensive car doesn’t just save money on the purchase.
It can reduce the amount of your financial life that needs protecting.
Of course, liability insurance is different. In Québec, for example, vehicle owners are legally required to carry private civil-liability insurance. The optional portion covering damage to your own vehicle is a separate question.
4. Rent instead of owning a house
I know this suggestion will annoy some people.
Homeownership is deeply embedded in our idea of financial success.
But owning property creates risks and expenses that renters can transfer to landlords.
The landlord generally bears responsibility for insuring the building itself. As a renter, I am obliged to buy rental insurace. If there is a fire in the building and my furniture is lost, I simply don’t care, it would give me an opportunity to buy new furniture.
5. Own fewer expensive possessions
There is another strategy that rarely gets mentioned:
Own less stuff worth insuring.
Expensive jewelry, luxury cars, vacation homes, boats and expensive collections create financial exposures.
Every expensive possession doesn’t just cost money to buy.
It can cost money to maintain, protect, store and insure.
let’s say you like boating and fancy cars. Just rent them for a couple of hours. Don’t pay for a boat insurance you will only a few weekends a year.
A simpler lifestyle can function as a form of risk reduction.
6. Maintain your health
Health is more complicated because medical systems differ enormously between countries.
Here in Canada, medically necessary hospital and physician services are largely covered through provincial healthcare systems, although many services, medications and other costs can fall outside public coverage.
Staying healthy isn’t a substitute for health or disability insurance where those protections are necessary.
But exercising, maintaining a healthy weight, eating well, sleeping adequately, avoiding tobacco and taking preventive health seriously can reduce many health risks—and provide benefits far beyond insurance costs.
Risk prevention is often better than risk transfer.
7. Build enough wealth that life insurance becomes unnecessary
Life insurance serves an important purpose when other people depend financially on your income.
Imagine a 35-year-old parent with young children, a mortgage and little savings. If that person dies, the financial consequences for the family could be enormous.
Life insurance can protect against that catastrophe.
But the calculation changes later in life.
Suppose your children are financially independent, you have no major debts and your surviving family would inherit substantial investments.
What exactly are you insuring?
At some point, your investment portfolio may become your life insurance policy.
Self-Insurance Gets Easier as You Become Wealthier
This creates an interesting financial cycle.
When you have very little money, you are vulnerable to relatively small financial shocks.
As you accumulate savings, you can increase deductibles, absorb repairs yourself, replace inexpensive possessions without filing claims and potentially eliminate insurance products you no longer need.
Eventually, wealth itself becomes a form of insurance.
That’s essentially where Munger ended up.
A house fire was a catastrophe for the house.
It wasn’t a financial catastrophe for Charlie Munger.
That distinction changed his decision.
Don’t Buy Peace of Mind You Already Own
My brief experience selling insurance taught me something that has stayed with me.
Fear sells.
“Peace of mind” sells even better.
But financial security can also provide peace of mind.
If replacing a $2,000 item wouldn’t meaningfully affect your life, you may not need to pay another company year after year to protect you from losing it.
Put some of those savings into your own financial reserves instead.
Over decades, your emergency fund and investment portfolio can gradually assume more of the job previously performed by insurance companies.
But never confuse self-insurance with simply being uninsured.
Self-insurance means you have deliberately evaluated a risk, decided you can absorb the worst reasonable outcome, and set aside sufficient financial resources to do so.
Going without protection because you don’t want to pay the premium while lacking the money to absorb the loss isn’t self-insurance.
It’s gambling.
Charlie Munger could write a check to rebuild his mansion.
Most of us can’t.
But we can borrow the principle behind his decision:
Insure the losses that could seriously damage your financial life. Consider self-insuring the losses that wouldn’t.
And as your wealth grows, keep asking whether you’re still paying someone else to protect you from risks you can now comfortably handle yourself.
Frequently Asked Questions
What is self-insurance?
Self-insurance means deliberately retaining a financial risk instead of paying an insurance company to assume it. You effectively use your own savings or assets to cover a potential loss.
How much money do I need before I can self-insure?
There is no universal amount. A useful test is whether paying the entire potential loss would materially damage your financial security, force you into debt, or prevent you from meeting important obligations.
Should I cancel my homeowners insurance if I can afford repairs?
Not necessarily. Repairs are different from a total loss, and homeowners policies may also cover liability and other risks. If you have a mortgage, your lender will generally require property insurance. Evaluate the maximum realistic loss, not merely routine repairs.
Is a high insurance deductible a form of self-insurance?
Yes. Choosing a higher deductible means you retain more of the smaller losses yourself while transferring catastrophic losses to the insurer. For financially secure households, this can be one practical way to combine self-insurance with protection against major risks.
Other personal finance blog posts
Leave a Reply