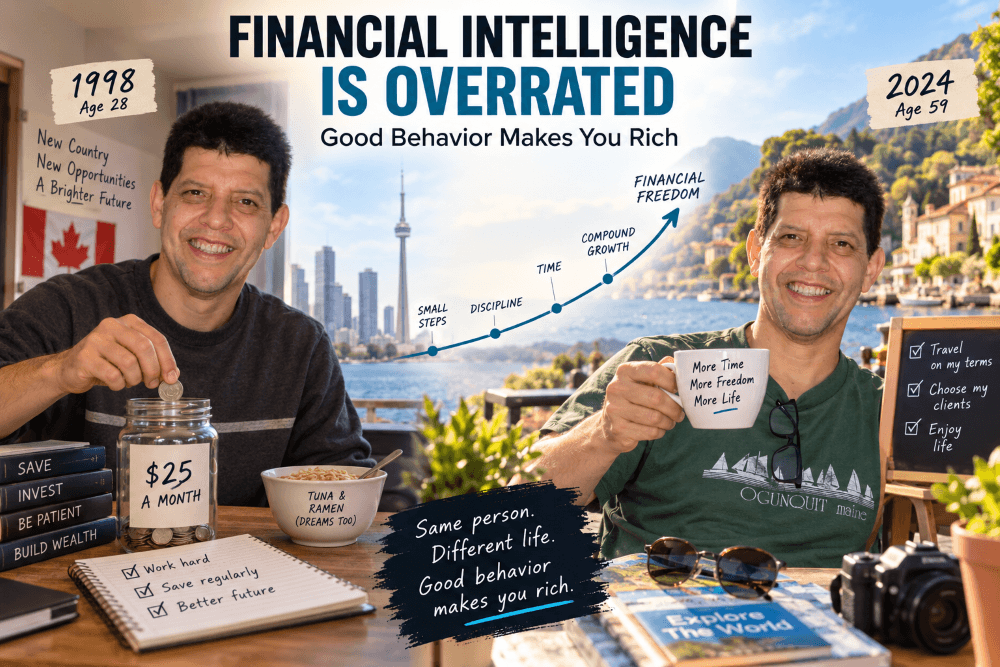
You don’t have to be a financial genius to become wealthy. In my experience, financial discipline matters far more than knowing how to analyze a balance sheet, predict interest rates, or find the next great stock.
I came to Canada in 1998. I didn’t have much money, sophisticated financial knowledge, or some brilliant investment strategy.
What I did have was the determination to save.
From practically the first day I arrived, I started putting money aside. Most of the time it was only $25 a month.
At the beginning, I was basically living on cans of tuna and ramen noodles. It wasn’t glamorous, but whenever I had a little money left over, I tried to put something into my investment account.
I continued doing that for more than 25 years.
By 2024, I looked at my finances and realized something remarkable: I had accumulated enough money that I could retire and live comfortably.
There was no financial genius behind it.
There was mostly discipline, patience, time, and consistency.
Here are five lessons I learned along the way.
1. Financial Discipline Matters More Than Intelligence
Personal finance is one of those areas where knowing what to do and actually doing it are two completely different things.
Most people already understand the basics:
- Spend less than you earn.
- Save regularly.
- Invest your savings.
- Avoid unnecessary debt.
- Don’t panic when markets fall.
- Give your investments time to grow.
None of those ideas requires a PhD in economics.
The difficult part is doing them year after year.
When I started saving $25 at a time, those contributions seemed almost insignificant. What could $25 possibly accomplish?
But the important thing wasn’t the $25.
The important thing was establishing the habit.
As my financial situation improved, I could save more. Investing became something normal rather than something I had to force myself to do.
That is the power of financial discipline. Small decisions repeated thousands of times can eventually produce surprisingly large results.
2. Looking Rich and Being Rich Are Very Different Things
I have never had much desire to look wealthy.
Maybe being a dance teacher helped.
My status symbol wasn’t a fancy automobile or an expensive watch. I wanted to be a good dancer.
That was much more important to me than showing people how much money I supposedly had.
Over the years, I often saw people around me who were struggling to pay their rent but still felt they needed fashionable clothes, an expensive mobile phone, or other visible symbols of success.
I never understood it.
One of the strange things about wealth is that much of it is invisible.
You can see someone’s $70,000 car. You cannot see the $70,000 sitting in someone else’s investment account.
The person driving the expensive car might be wealthy—or might have a large monthly payment.
Meanwhile, the person taking the bus might have a six-figure investment portfolio.
Stop Performing Wealth
There is an enormous financial advantage to not caring very much about impressing strangers.
Every dollar you don’t spend trying to look successful can become a dollar working toward actually becoming financially secure.
That doesn’t mean we shouldn’t enjoy money. I believe money exists to improve our lives.
But there is a difference between buying something because it genuinely brings you pleasure and buying something because you want other people to notice it.
Learning that distinction can be worth a fortune.
3. Time Is the Secret Ingredient in Building Wealth
Today something interesting is happening with my finances.
My wealth can grow faster than my expenses.
That didn’t happen because I suddenly became a brilliant investor. It happened because I have been saving and investing for such a long time.
Time is finally doing much of the work.
Suppose you invest $10,000 and earn an average return of 6%. After one year, the return is only about $600.
That’s nice, but it probably isn’t going to transform your life.
Give that money decades to compound, while continuing to add new savings, and the mathematics becomes much more interesting.
Eventually, your money starts producing meaningful amounts of money of its own.
This is why starting early is so valuable.
And if you didn’t start early, the second-best option is starting now.
You can’t go back and invest yesterday’s money. But you can give today’s money as many tomorrows as possible.
4. Always Leave Room for Things to Go Wrong
My financial life has never followed a perfectly straight line.
I have always been self-employed, which means I learned early that a good year doesn’t guarantee another good year.
So I planned accordingly.
At different moments in my life:
- I found additional sources of income.
- I worked as an Uber driver when I wanted extra money.
- I relied on savings when income was lower.
- I reduced expenses when circumstances required it.
- I took advantage of falling markets when I believed stocks had become attractive.
There were even times when markets dropped and, rather than running away from stocks, I borrowed money and bought more shares at lower prices.
That last strategy involves substantial risk and certainly isn’t appropriate for everyone, it requires faith that markets always recuperate, it could be in one week or in 5 years.
The broader lesson is much more important: your financial plan needs room for bad things to happen.
Jobs disappear. Clients leave. Businesses struggle. Cars break. Recessions happen. Stock markets crash.
A financial plan shouldn’t depend on everything going perfectly.
Savings don’t just build wealth. They create resilience.
5. The Best Thing Money Buys Is Control Over Your Time
People often associate wealth with things.
Bigger houses. Better cars. Luxury watches. Expensive restaurants.
Those things may be enjoyable, but one of the greatest luxuries money has given me is much less visible:
control over my time.
I like traveling during shoulder season, when there are fewer crowds and prices are often lower.
I can go grocery shopping when stores aren’t busy. I can visit coffee shops outside peak hours.
Those might sound like small things.
To me, they are wonderful.
I don’t have to organize my entire life around somebody else’s schedule.
Money Also Lets You Choose the People Around You
There is another form of freedom that I value even more.
I can decide whom I want to do business with.
If I have a client I don’t enjoy working with, I don’t necessarily have to continue that relationship simply because I desperately need the money.
That adds an enormous amount of joy to my life.
Financial independence gives you the ability to say no.
No to unpleasant clients.
No to work you hate.
No to unnecessary obligations.
No to people who make your life miserable.
That ability may be more valuable than anything sitting in a showroom window.
Financial Discipline Is Ultimately About Freedom
When I started saving after arriving in Canada in 1998, I wasn’t thinking about all these philosophical ideas.
I was simply trying to build a better financial future.
I saved $25 when $25 was what I could afford. Later I saved more.
I kept investing.
I lived through good markets and bad markets, good working years and difficult ones.
Then decades passed.
That last ingredient is easy to underestimate.
Financial discipline plus time can accomplish things that financial brilliance without discipline often cannot.
You don’t have to constantly find the best investment.
You don’t have to predict the next recession.
You don’t have to understand every movement in the stock market.
And you certainly don’t need to look rich.
You need to create a reasonable system and stick with it long enough for that system to work.
Save.
Invest.
Keep your expenses under control.
Prepare for bad years.
Avoid competing with other people over possessions.
Give compound growth decades rather than months.
And, perhaps most importantly, remember what all that money is ultimately for.
For me, the reward isn’t seeing a large number on an investment statement.
It’s waking up and having greater control over what I do, when I do it, and whom I do it with.
That’s wealth.
Frequently Asked Questions
What is financial discipline?
Financial discipline is the habit of consistently making decisions that support your long-term financial goals. It includes spending less than you earn, saving regularly, investing, controlling unnecessary debt, and avoiding emotional financial decisions.
Do you need to be financially intelligent to become wealthy?
You need some basic financial knowledge, but you don’t have to be an expert. Understanding saving, investing, diversification, risk, debt, and compound growth can be enough to build a strong foundation. Consistently applying those principles may matter more than sophisticated financial knowledge.
How much should I save if I don’t earn very much?
Start with an amount you can sustain. When I began, sometimes I could contribute only $25 a month. The initial amount matters less than creating the habit and increasing your savings as your financial situation improves.
What is the greatest benefit of financial independence?
For me, it is control. Financial independence can give you greater control over your time, your work, your schedule, and even the people with whom you choose to do business. Money is valuable not only for what it allows you to buy, but also for the choices it allows you to make.
Other personal finance blog posts
Leave a Reply