Weekly Market Review | AI records, an energy boom, and a bond-market warning
Wall Street finished the week higher, but the gains concealed growing weaknesses beneath the surface.
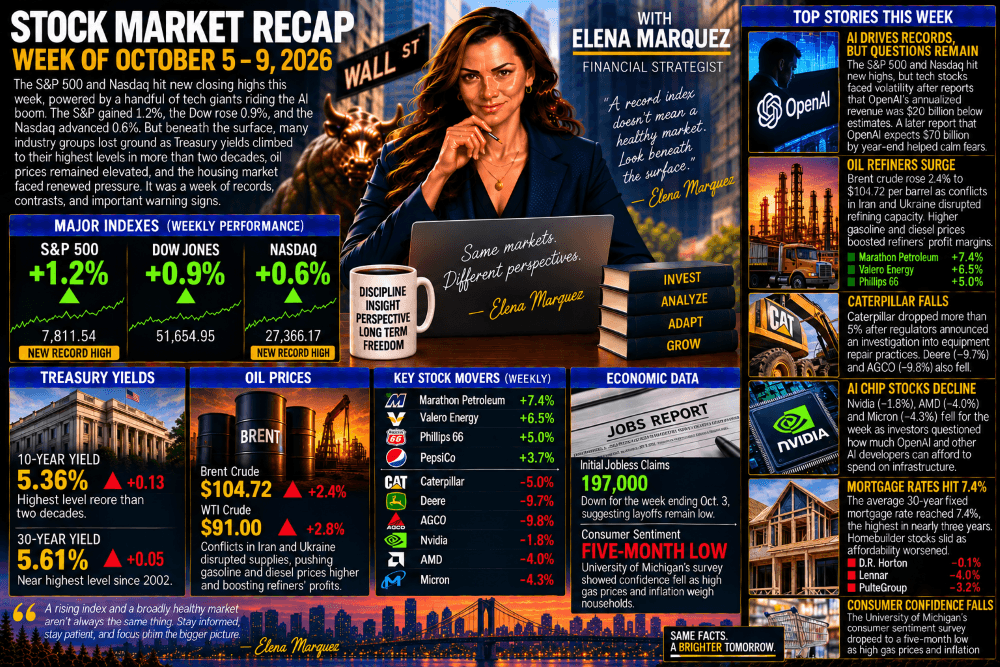
The S&P 500 and Nasdaq reached new closing records during the week, powered by enthusiasm for artificial intelligence and a small group of technology giants.
But rising Treasury yields, expensive oil, weakening housing affordability and concerns about AI profitability reminded investors that record stock prices don’t necessarily mean a healthy market.
S&P 500
+1.2%
Weekly return
Dow Jones
+0.9%
Weekly return
Nasdaq
+0.6%
Weekly return
Weekly percentage changes from October 5 through October 9, 2026, as provided.
The S&P 500 led the three major indexes, gaining 1.2%, followed by the Dow at 0.9% and the Nasdaq at 0.6%.
Yet some of the week’s most interesting developments occurred outside the major indexes.
Oil refiners surged. Construction-equipment manufacturers stumbled. Semiconductor stocks declined. And mortgage rates climbed to levels that threaten to make an already difficult housing market even worse.
1. The Stock Market’s Rally Is Narrower Than It Looks
The S&P 500 and Nasdaq reached new records this week.
Normally, that would suggest widespread optimism about corporate profits and the economy.
But there’s a problem.
Since the S&P 500’s previous record in August, many of its industry groups have actually declined.
A relatively small number of very large companies have been responsible for much of the index’s strength.
Nvidia, Apple and Microsoft alone represent roughly one-fifth of the S&P 500’s market capitalization.
That concentration matters because the S&P 500 is weighted by market capitalization.
A 2% gain in a company worth several trillion dollars can have a much larger impact on the index than a similar gain in a smaller company.
As a result, the index can reach a record even while many individual stocks struggle.
A rising index and a broadly healthy market aren’t necessarily the same thing.
2. The Bond Market Sends a Warning
One of the week’s most significant developments was the continuing selloff in government bonds.
The 10-year Treasury yield climbed above 5.3%, reaching its highest level in more than two decades.
Bond prices and yields move in opposite directions. When investors sell bonds, prices decline and yields rise.
Those higher yields affect borrowing costs throughout the economy.
Corporations pay more to issue debt. Banks face changing financing conditions. Real estate becomes more expensive to finance. Consumers face higher mortgage rates.
And for technology stocks, high interest rates reduce the present value of future earnings.
That’s particularly important when investors are paying enormous valuations for companies expected to generate substantial profits many years from now.
The AI boom may be real.
But financing it is becoming more expensive.
3. Winner of the Week: Oil Refiners

SECTOR SPOTLIGHT
Energy refiners surge
Conflicts involving Iran and Ukraine have disrupted global refining capacity and fuel supplies.
Gasoline and diesel prices have risen faster than crude oil, improving the profitability of companies that convert crude into finished fuels.
The key concept is the crack spread.
A crack spread measures the difference between the market value of refined petroleum products and the cost of the crude oil used to produce them.
When gasoline and diesel prices rise faster than crude prices, that spread widens.
Refiners can earn more money from each barrel they process, assuming their other costs and operating conditions remain favorable.
Brent crude finished the week around $104.72 per barrel, up approximately 2.4%.
But refined fuel prices increased even faster.
That helped push refinery stocks sharply higher.
Refinery stocks — weekly performance
0%2%4%6%8%Marathon PetroleumValero EnergyPhillips 66
Valero’s increase was reported as more than 6.5%; 6.5% is used as the chart’s conservative reference value.
Marathon Petroleum gained approximately 7.4%, Valero Energy rose more than 6.5%, and Phillips 66 advanced 5%.
Shares of all three companies have more than doubled this year, according to the supplied figures.
Analysts are expecting exceptionally strong third-quarter refining profits.
The lesson is interesting:
High oil prices don’t benefit every energy company equally. Sometimes the biggest winners are the companies processing the oil rather than producing it.
4. Loser of the Week: Caterpillar

STOCK SPOTLIGHT
Caterpillar falls more than 5%
Caterpillar has benefited from AI infrastructure investment, particularly demand for generators used to power data centers.
But this week, the company became caught in a broader selloff in agricultural and industrial equipment stocks.
Federal regulators announced an investigation into competition and equipment-repair practices.
The Federal Trade Commission and the Department of Agriculture are examining complaints from farmers about obstacles to purchasing equipment and obtaining maintenance services.
The concern is that restrictions on repairs and servicing may limit competition and increase costs for equipment owners.
The announcement weighed heavily on the sector.
Equipment stocks — weekly performance
-11%-8.25%-5.5%-2.75%0%CaterpillarDeereAGCO
Caterpillar’s decline exceeded 5%; −5% is shown as a reference point.
Deere fell 9.7%, AGCO declined 9.8%, and Caterpillar lost more than 5%.
Caterpillar was the Dow’s worst-performing stock of the week.
This illustrates an important investment principle.
Even companies benefiting from powerful long-term trends can suffer when regulatory risks emerge.
5. AI Stocks Face a Reality Check
Artificial intelligence has been one of the strongest investment themes of 2026.
But this week revealed a growing concern about the economics behind the boom.
The Financial Times reported that OpenAI’s annualized revenue was approximately $20 billion below earlier estimates.
That raised questions about how much AI developers can afford to spend on chips, data centers and computing infrastructure.
A subsequent Bloomberg report suggested OpenAI expects annualized revenue to reach or exceed $70 billion by year-end.
That helped calm some concerns, but semiconductor stocks still finished the week lower.
AI chip stocks — weekly performance
-5%-3.75%-2.5%-1.25%0%NvidiaAMDMicron
Nvidia declined 1.8%, AMD fell 4%, and Micron lost 4.3%.
These companies remain major beneficiaries of AI infrastructure spending.
But investors are increasingly distinguishing between two different questions:
Will artificial intelligence transform the economy?
And:
Will today’s investments in AI generate sufficient profits to justify their valuations?
The answer to the first question may be yes without every investment succeeding.
That distinction could become increasingly important as the AI boom matures.
6. Number of the Week: 7.4%
Average 30-year fixed mortgage rate, as reported
7.4%
Highest level in nearly three years
The surge in mortgage rates is becoming a serious problem for the US housing market.
Higher rates dramatically increase the monthly cost of buying a home.
Consider a buyer borrowing $400,000 over 30 years.
What higher mortgage rates mean
Interest rate
7.4%
Monthly principal and interest
$2,770
30-year loan, $400,000 principal, excluding taxes and insurance
At 5%, the same loan costs approximately $2,147 per month. At 7.4%, it costs approximately $2,769 — about $622 more every month.
That difference can price many households out of the market.
Homebuilders are responding by offering incentives, mortgage-rate buydowns and discounts.
Existing-home sellers are also feeling pressure.
According to Redfin, approximately 21% of sellers reduced their asking prices during a four-week period ending in September.
That suggests the market is increasingly favoring buyers who can afford today’s financing costs.
7. Homebuilders Come Under Pressure
Higher mortgage rates weighed on homebuilding stocks.
| Company | Weekly return |
|---|---|
| D.R. Horton | −0.1% |
| Lennar | −4.0% |
| PulteGroup | −3.2% |
| State Street homebuilder ETF | ~−2.0% |
The problem isn’t simply that homes are expensive.
It’s that financing those homes has become significantly more expensive.
For homebuilders, this creates a difficult tradeoff.
They can maintain selling prices and risk weaker demand.
Or they can offer discounts and incentives that reduce profit margins.
Neither is attractive.
And if Treasury yields remain elevated, the pressure may continue.
8. What to Watch Next Week
The next major catalyst is third-quarter earnings season.
Major Wall Street banks are scheduled to begin reporting Tuesday, October 13.
Investors will be looking for evidence that corporate profits can justify record stock prices.
Three questions will be especially important.
First: Are banks seeing signs of deteriorating consumer credit or business borrowing?
Second: Can energy companies convert higher fuel prices into stronger profits?
Third: Will technology companies demonstrate that AI revenue is growing fast enough to justify enormous infrastructure spending?
Those answers could determine whether the market’s rally broadens or becomes even more dependent on a handful of technology giants.
The Bottom Line
| S&P 500 | +1.2% |
| Dow Jones | +0.9% |
| Nasdaq | +0.6% |
| Brent crude | $104.72 (+2.4%) |
| Marathon Petroleum | +7.4% |
| Caterpillar | More than −5% |
| Nvidia | −1.8% |
| 30-year mortgage rate | 7.4% |
This was a week of contrasts.
Major stock indexes rose, but many individual companies struggled.
AI optimism helped push the market to records, yet semiconductor stocks finished the week lower.
Higher oil prices hurt consumers but created extraordinary opportunities for refiners.
Rising Treasury yields pressured housing and industrial companies while investors continued paying premium valuations for technology stocks.
The biggest lesson is that the stock market is not the economy—and the S&P 500 is not every stock in the market.
As earnings season approaches, investors should look beyond headline index returns.
The companies delivering sustainable profits may increasingly distinguish themselves from those benefiting primarily from market enthusiasm.
Other Stock Market blog posts
Leave a Reply