Monthly Market Review | October 1–30, 2026
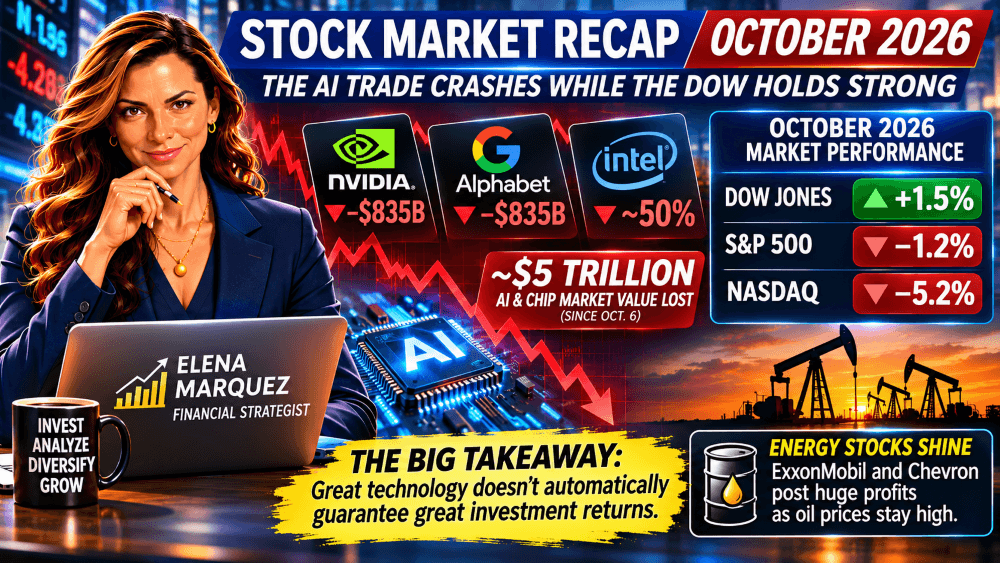
October 2026 delivered a striking contradiction on Wall Street: artificial intelligence stocks suffered a brutal selloff, yet the broader market proved surprisingly resilient.
The biggest AI and semiconductor companies collectively lost an estimated $5 trillion in market capitalization from October 6 through the end of the month, according to Yahoo Finance calculations. Nvidia and Alphabet each surrendered roughly $835 billion in market value, while Intel reportedly lost nearly half its value during October.
The technology-heavy Nasdaq Composite fell approximately 5.2%, its worst monthly performance since March 2025. The S&P 500 declined a more modest 1.2%, while the Dow Jones Industrial Average actually gained 1.5%.
What explains this extraordinary divergence?
Investors began questioning whether the hundreds of billions of dollars being poured into artificial intelligence infrastructure would generate adequate returns. Higher financing costs, disappointing technology earnings, and concerns about AI profitability helped transform enthusiasm into skepticism.
But outside the AI trade, the stock market showed signs of strength.
Energy companies benefited from high oil prices, established businesses attracted investors seeking stability, and the Dow managed to finish the month in positive territory.
October was not simply a stock market correction. It was a reminder that a revolutionary technology doesn’t automatically guarantee profitable investments.
1. How the Major Indexes Performed in October
How the Major Indexes Performed in October
October 1–30, 2026 | Monthly Stock Market Performance
The Nasdaq’s 5.2% decline reflected a sharp reassessment of technology companies, particularly those associated with artificial intelligence.
The S&P 500 held up considerably better, declining only 1.2%.
Meanwhile, the Dow gained 1.5%.
This divergence suggests that investors weren’t necessarily abandoning stocks altogether. Instead, they were becoming more selective about where to invest.
Companies with established earnings, reliable cash flows and less exposure to expensive AI infrastructure projects became relatively more attractive.
2. The $5 Trillion AI Selloff
October’s defining story was the collapse in market valuations across some of the world’s largest AI-related companies.
According to Yahoo Finance calculations, major AI and semiconductor stocks collectively lost approximately $5 trillion in market value after October 6.
The AI Market Value Wipeout
Reported losses from October 6 through month-end
Major AI and chip stocks combined
~$5T
Estimated market value lost
Nvidia
~$835B
Reported market value lost
Alphabet
~$835B
Reported market value lost
Intel
~50%
Reported October share-price decline
The $5 trillion figure covers a basket of major AI and chip stocks, not the entire stock market. Figures are approximate and should not be added together.
These losses are staggering.
For perspective, $5 trillion exceeds the annual economic output of most countries.
But there’s an important distinction.
A decline in market capitalization doesn’t mean companies physically lost $5 trillion in cash.
It means investors were no longer willing to pay the same prices for ownership in those businesses.
Stock valuations depend not only on current profits but also on expectations about future earnings.
When those expectations change, prices can adjust rapidly.
Why investors became nervous
Artificial intelligence requires enormous infrastructure investment.
Companies are spending billions on graphics processors, data centers, electricity, cooling systems and specialized networking equipment.
The expectation has been that these investments will eventually generate substantial profits.
But October brought renewed questions about the timing and magnitude of those returns.
The market began asking whether AI spending was growing faster than the profits it could reasonably generate.
3. Semiconductor Stocks Enter a Sharp Correction
Semiconductor stocks experienced one of the most dramatic corrections of the month.
The iShares Semiconductor ETF (SOXX) reportedly declined approximately 17% in October.
Yet despite that sharp decline, the ETF remained up more than 50% for the year, according to the supplied figures.
Semiconductor Stocks: October vs. 2026
SOXX — October
−17%
Approximate monthly change
SOXX — Year to date
+50%+
Reported gain despite October decline
This is an important reminder about market volatility.
An investment can fall sharply in a single month while remaining substantially higher than it was at the beginning of the year.
After an extended rally, expectations can become extremely optimistic.
Even a modest disappointment may then trigger a major correction.
Is this a bear trap?
Some investors are wondering whether October’s semiconductor selloff could prove to be a bear trap.
A bear trap occurs when prices fall sharply, encouraging investors to expect further declines, only for the market to reverse and rise.
Historically, semiconductor stocks have experienced dramatic corrections during longer-term advances.
However, a sharp decline doesn’t automatically mean a recovery is imminent.
Semiconductor companies remain vulnerable to changes in capital spending, demand for AI infrastructure, interest rates and investor expectations.
The October correction may eventually prove to be a buying opportunity.
It could also be the beginning of a longer period of weakness.
Nobody knows which outcome will occur.
4. Alphabet, Nvidia and Intel Lead the Decline
Nvidia: The AI boom’s biggest symbol
Nvidia became one of the most prominent casualties of October’s reassessment of AI valuations.
The company reportedly lost approximately $835 billion in market capitalization after October 6.
Nvidia has been one of the largest beneficiaries of the AI infrastructure boom.
Its advanced processors power many of the world’s most sophisticated AI systems.
But even companies benefiting from extraordinary demand can become vulnerable when their stock prices reflect exceptionally high expectations.
The question isn’t whether Nvidia makes valuable products.
It’s whether future profits will justify the valuation investors are paying today.
Alphabet: AI spending meets disappointing earnings
Alphabet also reportedly lost roughly $835 billion in market capitalization during the selloff.
The company suffered an especially painful decline after its quarterly earnings disappointed investors.
Alphabet’s October losses reflected concerns about its core search business and the costs of expanding AI infrastructure.
Investors became increasingly concerned that spending on data centers and specialized processors could reduce free cash flow before generating substantial additional profits.
The company remains a dominant force in digital advertising and cloud computing.
But dominance doesn’t eliminate the risk of overinvestment.
Intel: Almost half its market value disappears
Intel suffered one of the month’s most severe declines.
According to the supplied report, its shares lost nearly half their value during October.
Intel’s difficulties reflected disappointing earnings, weaker PC demand and industry supply-chain challenges.
Its stock plunged almost 29% on October 30 following its earnings announcement.
The collapse illustrated that the semiconductor industry is not one uniform business.
Different manufacturers have very different exposures to AI demand, traditional computing, manufacturing costs and competitive pressures.
5. The Federal Reserve and the Cost of AI Infrastructure
On October 28, the Federal Reserve left interest rates unchanged.
The decision was expected, but it reinforced an important challenge facing technology companies.
Building AI infrastructure requires enormous amounts of capital.
Many companies are financing these investments through borrowing, partnerships and internally generated cash flow.
When borrowing costs are elevated, projects become more expensive.
A data center that looked profitable under one set of financing assumptions may become much less attractive when interest rates rise.
Higher interest rates can also reduce the present value of profits expected many years into the future.
That makes highly valued growth stocks particularly sensitive to changes in interest-rate expectations.
October’s AI selloff wasn’t necessarily a rejection of artificial intelligence.
It was partly a reassessment of the financial economics required to turn AI innovation into shareholder profits.
6. The Dow’s Resilience: Not Every Sector Was Selling Off
While AI-related stocks experienced severe declines, the Dow Jones Industrial Average gained approximately 1.5% in October.
This was one of the month’s most revealing developments.
It suggested that investors were shifting capital rather than abandoning equities altogether.
Companies with established earnings, strong cash flow and less exposure to speculative growth expectations were relatively more attractive.
The energy sector provided a clear example.
ExxonMobil and Chevron benefit from high oil prices
ExxonMobil and Chevron reported exceptional third-quarter earnings.
ExxonMobil earned approximately $15.4 billion, while Chevron reported around $9.9 billion, according to the supplied figures.
Higher oil prices and strong refining margins supported profits.
Brent crude ended October near $113 per barrel amid concerns about geopolitical instability and disruptions to energy infrastructure.
Oil companies benefited from conditions that were creating additional costs for consumers and many other businesses.
The divergence highlights an important investing principle: economic developments rarely affect every industry in the same way.
7. October’s Historical Context: The Midterm Election Pattern
One of the more interesting arguments for stock-market optimism comes from historical election-cycle data.
According to a Yahoo Finance analysis, the S&P 500 has risen from the final October close of a U.S. midterm election year through the following June in every such period since 1950.
The Historical Midterm-Year Pattern
Final October close through the following June
S&P 500 historical record
19 / 19
Positive periods since 1950
Median S&P 500 gain
+15%
Historical median
Semiconductor historical record
8 / 8
Positive periods since 1994
Median semiconductor gain
+22%
Historical median
Historical figures attributed to Yahoo Finance’s election-cycle analysis. Past performance does not predict future returns.
At first glance, these numbers appear extremely encouraging.
But there are several reasons for caution.
First, historical patterns are not guarantees.
Second, the semiconductor sample contains only eight observations.
Third, even when markets ultimately recovered, investors sometimes experienced substantial additional declines first.
For example, semiconductor stocks reportedly fell another 11% before eventually recovering during the 2002 and 2018 cycles.
A historical tendency toward higher prices doesn’t tell investors exactly when to buy.
Nor does it eliminate the possibility of further losses.
The lesson is to treat historical statistics as context, not as a trading system.
8. The Most Important Lesson of October: Valuation Matters
October 2026 highlighted a distinction that investors sometimes forget during periods of technological excitement.
A company can create extraordinary technology without necessarily producing extraordinary shareholder returns.
Consider a hypothetical AI company that spends $100 billion building infrastructure.
If the investment eventually generates $20 billion in additional annual profits, it may prove highly attractive.
But if it generates only $3 billion, shareholders may be disappointed.
The technology could still be useful.
Customers could still benefit.
The broader economy could still become more productive.
Yet the financial returns might not justify the original investment.
That’s why investors must evaluate not only revenue growth and technological leadership but also free cash flow, capital expenditures, profit margins and return on invested capital.
October’s selloff suggested that Wall Street was beginning to demand stronger evidence of financial discipline.
9. What Investors Should Watch in November
November begins with a market divided between weak AI-related stocks and relatively resilient parts of the broader economy.
Several developments could influence the next phase.
- AI earnings and capital spending: Will technology companies demonstrate that their infrastructure investments are generating attractive returns?
- Semiconductor demand: Will the sharp October correction stabilize, or will investors continue reducing exposure?
- Federal Reserve policy: Will inflation and economic data give the Fed room to reduce borrowing costs?
- Oil prices and geopolitics: Could further disruptions in energy markets create inflationary pressure?
- Market breadth: Will gains spread across more industries, or will technology weakness eventually affect the broader market?
- Midterm election seasonality: Will the historically strong November-to-June period repeat, or will this cycle prove different?
These questions are more important than attempting to predict the market’s exact next move.
The Bottom Line: The AI Revolution Is Real, but Prices Still Matter
October 2026 was a difficult month for investors concentrated in artificial intelligence and semiconductor stocks.
An estimated $5 trillion in market capitalization disappeared from major AI-related companies after October 6.
The Nasdaq fell 5.2%.
Semiconductor stocks declined approximately 17%.
Intel reportedly lost nearly half its value.
Yet the Dow gained 1.5%, showing that much of the broader market remained resilient.
History offers some encouragement for the months ahead, particularly around U.S. midterm election cycles.
But investors should be careful not to confuse historical averages with guaranteed outcomes.
The most important takeaway from October is that even revolutionary technologies must eventually produce attractive financial returns.
Artificial intelligence may transform the world. But the price investors pay for that transformation will determine whether it becomes a great investment.
Other Stock Market blog posts
Leave a Reply