We are constantly told to stop comparing ourselves to others. Financial comparison, in particular, is often portrayed as a dangerous habit that leads to jealousy, anxiety, and unhappiness.
But I disagree with the idea that all financial comparison is bad.
In fact, comparing my financial situation with that of other Canadians has been one of the most useful tools in my financial journey.
It has helped me set goals, measure progress, increase my ambitions, and eventually work toward financial independence.
The problem isn’t comparing ourselves with others. The problem is comparing ourselves without a purpose.
Financial Comparison Can Be a Powerful Motivator
When I first came to Canada, I didn’t have grand financial ambitions. I wasn’t dreaming about becoming a millionaire, buying luxury cars, or retiring early.
My first financial goal was much simpler.
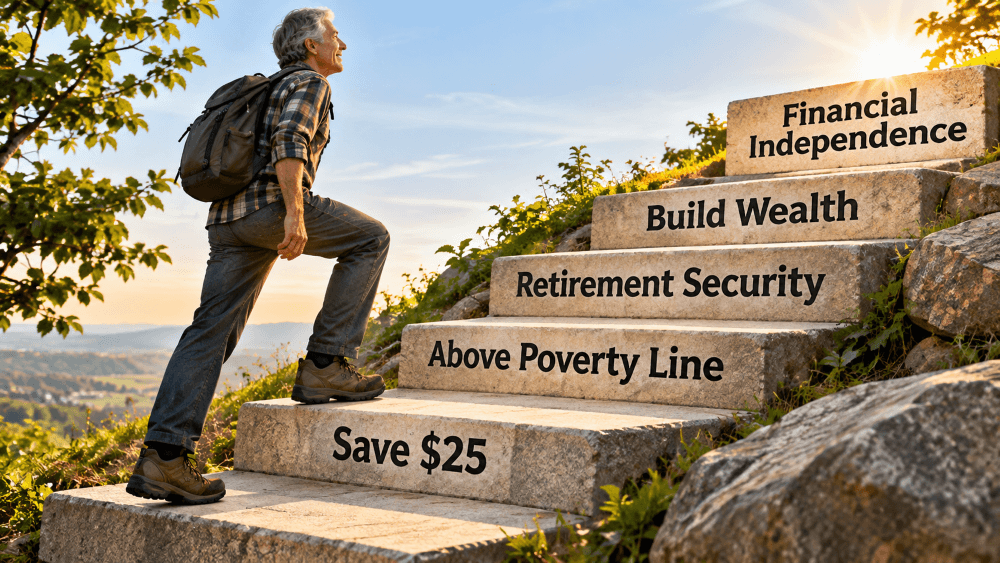
I wanted to figure out the minimum amount of money I needed to survive while still saving at least $25 per month.
That was it.
I wanted to earn enough to cover my basic expenses and have a little money left over. Saving $25 might not sound impressive today, but at the time, it represented something important: I was spending less than I earned.
Once I figured out how to accomplish that goal, I began looking for another benchmark.
And then another.
Over time, those small comparisons helped me develop increasingly ambitious financial goals.
My Financial Journey: One Benchmark at a Time
Looking back, I can identify several stages in my financial development.
Each stage involved comparing my financial situation with an external benchmark and asking myself how I could reach the next level.
1. Surviving and Saving $25 a Month
My first challenge was figuring out the minimum income I needed to live in Canada.
I calculated my expenses, examined my lifestyle, and tried to determine how little I could spend without sacrificing the essentials.
But I also wanted to save something.
Even if it was only $25 per month, I wanted to establish the habit of accumulating money rather than consuming everything I earned.
The amount was small, but the psychological achievement was enormous.
I had moved from merely surviving to beginning to build wealth.
2. Getting Above the Poverty Line
My next benchmark was Canada’s official measure of poverty.
I wanted to know how much money a person needed to earn to avoid being considered poor.
Canada’s official poverty line is based on the Market Basket Measure, which estimates the cost of a basket of basic goods and services. The threshold varies depending on location and household size.
I wanted to make sure my income was above that benchmark.
This wasn’t about looking down on people who earned less than me. It was about establishing a measurable financial objective.
I had identified a threshold, and I wanted to cross it.
3. Saving Enough for Retirement
Once I felt reasonably comfortable with my immediate financial situation, I started thinking about the future.
How much money would I need to retire without worrying about running out of savings?
What was the minimum amount I needed to accumulate to support myself in old age?
I wasn’t necessarily trying to become wealthy. I simply wanted to make sure I wouldn’t starve when I could no longer work.
This introduced a different type of financial comparison.
Instead of comparing my income with other people’s incomes, I began comparing my retirement savings with the amount I would eventually need.
The benchmark had changed from survival today to security tomorrow.
4. Reaching the Middle Class
Eventually, I became interested in another question.
What does it mean to be middle class in Canada?
How much does the average Canadian earn? What is the median household income? What kind of lifestyle can a middle-class income support?
There is no single universally accepted income threshold for being middle class, but income statistics provide useful reference points.
I wanted to know where I stood.
And once I understood the numbers, I wanted to improve my position.
Again, financial comparison gave me a concrete target.
Instead of vaguely wishing to earn more money, I could establish a goal based on the economic reality around me.
5. Aiming for the Top 10%
As my financial situation improved, my ambitions continued to evolve.
I began wondering what level of income or wealth would place someone among the richest 10% of Canadians.
This was a much more ambitious benchmark than saving $25 per month.
But the principle remained exactly the same.
I wanted to understand where I stood and what it would take to reach the next level.
It’s important to distinguish between income and wealth. Someone can have a high salary but little accumulated wealth, while a retiree can have substantial investments and relatively modest annual income.
Both measurements are useful, but they tell different stories.
For me, the value of these comparisons was never simply the prestige of belonging to a particular group.
It was the motivation to keep improving.
6. Learning How Much I Can Spend in Retirement
Today, my financial questions are very different from the ones I asked when I first arrived in Canada.
I no longer focus exclusively on how much I can save or accumulate.
Instead, I ask:
How much money can I comfortably spend every year while maintaining a healthy retirement portfolio?
This represents an important change in perspective.
For much of my life, the objective was accumulation. Now, the objective is to enjoy the resources I have built without jeopardizing my financial security.
I consider factors such as investment returns, inflation, retirement income, longevity, and the amount of money I want to leave behind.
The goal is no longer simply to have more.
The goal is to make the best possible use of what I have.
And once again, financial benchmarks help me make better decisions.
Why You Should Compare Yourself With Someone Just Ahead of You
One of the most useful lessons I’ve learned is that we should compare ourselves with people who are slightly ahead of us financially.
Not necessarily with billionaires, celebrities, or the richest people in the world.
Instead, look at someone who has achieved the next realistic milestone.
If you’re struggling to save your first $1,000, learn from someone who has already built a $5,000 emergency fund.
If you have $20,000 invested, study the habits of someone who has accumulated $100,000.
If you’re approaching retirement, learn from someone who has successfully transitioned from accumulating investments to living off them.
The most useful comparison is often with someone whose success feels achievable.
Their progress can provide a roadmap for your own.
You can ask practical questions: What did they do differently? How much did they save? What habits helped them? What mistakes did they avoid?
Instead of feeling envious, become curious.
Why Comparing Yourself to Elon Musk Is Usually Pointless
I admire Elon Musk for what he has accomplished.
He has built and led businesses that have transformed major industries. His ambitions, willingness to take risks, and ability to pursue extraordinarily difficult projects are remarkable.
But comparing my financial success with his would serve almost no useful purpose.
We have different talents, personalities, opportunities, ambitions, and priorities.
We are also willing to make different sacrifices.
Building enormous businesses can require extraordinary work commitments, financial risks, public scrutiny, and stress.
I have no desire to organize my life around the pursuit of becoming one of the richest people in the world.
I value my friendships, social life, health, personal interests, and freedom.
Of course, I would enjoy having more money. Most people would.
But there is an important question we should ask whenever we admire someone else’s success:
Am I willing to pay the price they paid to achieve it?
We often admire the rewards without considering the sacrifices.
We see the enormous fortune, but we don’t necessarily see the sleepless nights, failed relationships, personal risks, or years of intense work that might accompany extraordinary success.
And even if we were willing to make those sacrifices, there is no guarantee we would achieve the same results.
Success also depends on timing, opportunity, luck, and circumstances beyond our control.
That’s why comparing ourselves with extreme outliers is often less useful than learning from people whose situations resemble our own.
Financial Comparison Should Inspire Action, Not Envy
There is a significant difference between productive and destructive financial comparison.
Destructive comparison sounds like this:
- My neighbour has a nicer house. I feel unsuccessful.
- My friend earns twice as much as I do. Life is unfair.
- Someone my age has a million dollars. I’m falling behind.
Productive comparison asks different questions:
- What financial habits helped my neighbour afford that house?
- What skills could I develop to increase my income?
- What investment strategy helped my friend accumulate wealth?
- What can I realistically do over the next five years to improve my situation?
The difference is enormous.
One approach generates resentment. The other generates ideas.
Comparison becomes valuable when it leads to learning and action.
It can also help us discover that we are already doing well.
Perhaps we earn less than our friends but save a higher percentage of our income.
Perhaps our net worth is modest, but we have no debt and enjoy tremendous freedom.
Perhaps we could earn considerably more money, but doing so would require sacrificing activities that make us happy.
Financial comparison should help us make informed choices, not force us to adopt someone else’s definition of success.
How to Use Financial Comparison to Improve Your Life
If you want to turn financial comparison into a constructive habit, I suggest following a simple process.
Step 1: Understand your current position.
Calculate your income, expenses, savings rate, debts, and net worth. You cannot measure progress without knowing your starting point.
Step 2: Identify the next realistic milestone.
Perhaps it’s saving $1,000, eliminating credit card debt, reaching a $100,000 investment portfolio, or earning the median income in your profession.
Step 3: Find an appropriate benchmark.
Look at reliable statistics or learn from people who have already achieved what you’re trying to accomplish. Make sure you’re comparing similar situations, including household size, age, and cost of living.
Step 4: Understand what success requires.
Determine the habits, skills, savings, investments, or lifestyle adjustments necessary to reach your goal.
Step 5: Decide whether the goal is worth the sacrifice.
Not every financial achievement is worth pursuing. Sometimes the additional income requires more stress, less leisure, or sacrifices you’re unwilling to make.
Step 6: Celebrate progress and choose your next goal.
Once you’ve achieved a milestone, recognize your accomplishment before moving on.
You don’t need to spend your entire life chasing the next number.
At some point, the objective may shift from accumulating more wealth to enjoying what you’ve already accumulated.
The Real Purpose of Financial Comparison
When I look back at my financial journey, I realize that comparison has played a positive role at almost every stage.
First, I wanted to survive and save $25 per month.
Then I wanted to rise above the poverty line.
Then I wanted enough savings to retire securely.
Then I wanted to reach middle-class financial benchmarks.
Then I wanted to understand what it would take to reach the top 10% of Canadians.
And today, I want to understand how much I can spend while enjoying a financially secure retirement.
Each question helped me move forward.
Each benchmark encouraged me to think a little bigger.
But my ultimate objective was never to become the richest person in the room.
It was to gain more control over my life.
I believe most of us would benefit from looking around, assessing where we stand, and identifying the next realistic step.
We shouldn’t compare ourselves with others to feel superior or inferior.
We should compare ourselves to learn what’s possible.
Look at the person one step ahead of you. Learn how they got there. Decide whether you want what they have. And if you do, figure out how to take that next step.
That’s how financial comparison can become a tool for building wealth, independence, and a better life.
Frequently Asked Questions
Is comparing your finances with others healthy?
Yes, when the comparison helps you learn, establish realistic goals, and make better financial decisions. It becomes unhealthy when it leads to constant envy, anxiety, or feelings of inadequacy.
What financial benchmarks should I compare myself against?
Useful benchmarks include your savings rate, net worth, debt levels, median income for your age or profession, retirement savings, and financial independence goals. Choose benchmarks relevant to your circumstances rather than comparing yourself indiscriminately with everyone.
How do I know if I’m financially successful?
Financial success depends on your personal objectives. For some people, it means earning a high income or accumulating substantial wealth. For others, it means having no debt, enjoying meaningful work, or possessing enough investments to retire comfortably.
Should I compare my net worth with people my age?
Comparing net worth with people in your age group can provide useful context, especially when planning for retirement. However, differences in family circumstances, inheritance, housing markets, career paths, and lifestyle choices mean these comparisons should be treated as reference points rather than judgments of personal success.
Other personal finance blog posts
Leave a Reply